PaymentsJournal
No Result
View All Result
SIGN UP
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
PaymentsJournal
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
No Result
View All Result
PaymentsJournal
No Result
View All Result

Bank of America Reports Strong Zelle Transaction Growth

By Sarah Grotta
August 21, 2019
in Analysts Coverage, Commercial Payments, Credit, Debit, Faster Payments
0
4
SHARES
0
VIEWS
Share on LinkedIn
CECL Credit Card, Zelle

CECL for Nerds and Credit Card Managers

While traditional financial institutions have long been the primary way to send and receive money, the rise of peer-to-peer (P2P) payment platforms has created a new way to handle financial transactions. P2P payments allow individuals to send and receive money directly from one another, without the need for a bank or other third party. Where does Zelle fit in this?

Bank of America published some new statistics today on the growth of its customers’ use of person-to-person (P2P) app, Zelle. There is still a lot of transaction growth, even two years after its initial launch. Here are the stats on Bank of America’s Zelle activity:

  • So far this year, Bank of America has sent and received 163 million transactions. That’s up 4% over transactions recorded in all of last year.
  • By last count, they have 8.4 million clients who are active on Zelle, meaning they sent or received a transaction in the last 90 days.
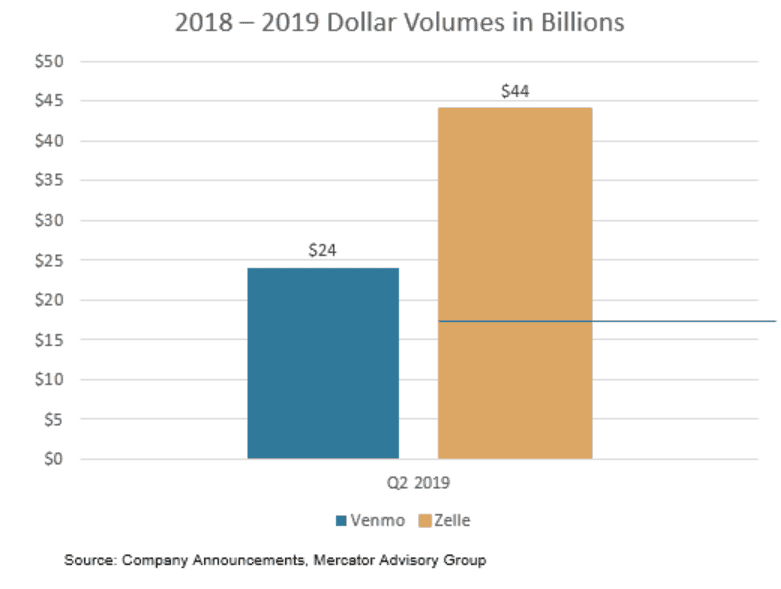
  • In second quarter alone, they processed 60 million transactions and $18 billion in transaction value with an average transaction amount of $268. The number of transactions are up by nearly 50% over last year.

How does this compare with Zelle volumes overall and Pay Pal’s reported Venmo volumes? We have a chart for that:
Bank of America also reported who is using Zelle and how:

Adoption of Zelle is increasing across all generations of Bank of America clients, including 68 percent of millennials and Gen Z, 20 percent of Gen X, and 12 percent of baby boomers and seniors.

Bank of America clients are using Zelle most often for paying rent, splitting utilities, family care and gifting.

Since offering Zelle to eligible Bank of America small business clients in June 2019, 180,000 small business owners have used their small business accounts to send money using Zelle.

The continued growth of Zelle demonstrates how quickly P2P payments are becoming part of consumers’ everyday financial lives. Bank of America customers are using the service for practical purposes such as paying rent, splitting household expenses, supporting family members, and sending gifts, while adoption is spreading across generations.

The expansion of Zelle to small business customers also illustrates how P2P payment platforms can move beyond their original consumer-to-consumer use cases. As transaction volumes continue to rise, services such as Zelle are becoming an increasingly important part of the broader digital payments ecosystem and an important way for banks to keep customers engaged within their own digital banking platforms.

Overview by Sarah Grotta, Debit and Alternative Products Advisory Service at Mercator Advisory Group

4
SHARES
0
VIEWS
Share on LinkedIn
Tags: Bank of AmericaFaster PaymentsP2PZelle

    Get the Latest News and Insights Delivered Daily

    Subscribe to the PaymentsJournal Newsletter for exclusive insight and data from Javelin Strategy & Research analysts and industry professionals.

    Must Reads

    hardware-bound payment card authentication

    Why Authentication Is a Revenue Strategy, Not Just a Fraud Control

    October 29, 2026
    credit union small business banking

    How Credit Unions Can Win Over Small Businesses

    October 28, 2026
    global stablecoin adoption

    A Global View: Why Stablecoins Look Different in Every Market

    October 27, 2026
    stripe stablecoin

    Stablecoins and the Threat to Traditional Bank Deposits

    October 26, 2026
    global cross-border payment infrastructure

    A New Payment Rail Is Not a Global Payment Solution

    October 23, 2026
    stablecoins in banking

    As Stablecoins Mature, Financial Institutions Face a Crossroads

    October 22, 2026

    Automation to Accountability: Governing AI in Fraud and Disputes 

    October 21, 2026
    google solana agentic

    Agentic Commerce Is Still Hype Ahead of Reality

    October 20, 2026

    Linkedin-in X-twitter
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter

    ©2026 PaymentsJournal.com |  Terms of Use | Privacy Policy

    • Commercial Payments
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    No Result
    View All Result
