PaymentsJournal
No Result
View All Result
SIGN UP
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
PaymentsJournal
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
No Result
View All Result
PaymentsJournal
No Result
View All Result

How Will Brexit Impact U.K. Banks?

By Steve Murphy
February 25, 2020
in Analysts Coverage, B2B Payments, Commercial Payments
0
7
SHARES
0
VIEWS
Share on LinkedIn

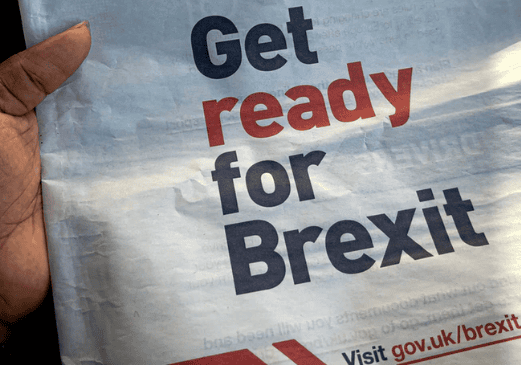
In this brief piece posted in PaymentsSource, the author  points out that a No Deal Brexit (which in effect has already happened, although there is a ‘transition period’ to work out trade deal specifics) will likely have quite a negative impact on UK businesses, including FIs, in terms of increased costs.  While this was sort of already baked into the Brexit cake, the actual final result will not be known for some time.

‘Without a deal in the making, the U.K. will lose its EU passporting rights, meaning banks and traditional financial institutions are likely to hit clients with international fees for every EU transaction. The U.K. government even predicts that credit card transaction fees will rise. Fintech companies, on the other hand, have essentially created a pseudo-open international market, enabling easy, quick cross-border financial transactions at a minimal cost. They will be key players in ensuring effortless trade between the U.K. and EU and will likely experience an upswing — particularly B2B payment companies.’

The author goes on to discuss the opportunities on the other side, which include fintech partnerships, new services, increased use of APIs (although this is basically what PSD2 is all about, and UK FIs have been a bit out ahead of the pack here anyway). 

The observation that U.S. fintechs have an opportunity to expand in the U.K. is interesting, although the most recent activity suggests EU (and UK) fintechs and challenger banks are attempting expansion into the U.S. (e.g.; Monzo, N26, Revolut, etc). In the end, it is expected that overall efforts will be a boon for B2B payments solutions, something that has been underway for a couple of years and shows no signs if expiring soon.

‘With any big change comes both opportunities and challenges and fintechs that view Brexit as opportunistic, particularly in the space of B2B payments, banking services and API technologies, are most likely to succeed.’

Overview by Steve Murphy, Director, Commercial and Enterprise Payments Advisory Service at Mercator Advisory Group

7
SHARES
0
VIEWS
Share on LinkedIn
Tags: B2BB2B PaymentsBrexitEnglandFinancial InstitutionUnited Kingdom

    Get the Latest News and Insights Delivered Daily

    Subscribe to the PaymentsJournal Newsletter for exclusive insight and data from Javelin Strategy & Research analysts and industry professionals.

    Must Reads

    first-party fraud prevention

    How Automation Is Changing the Fight Against First-Party Fraud

    November 11, 2026
    agentic payments governance

    From Know Your Agent to Govern Your Agent: Building the Control Layer for B2B Agentic Payments

    November 10, 2026
    merchant management APIs

    How Merchant Management APIs Are Streamlining Operations

    November 9, 2026
    digital wallet threats

    Why Digital Wallet Security Is Becoming More Complex

    November 6, 2026
    faster payments, Synchrony

    Just How Large Is the Potential Market for Stablecoins?

    November 5, 2026
    agentic commerce strategy

    Will There Be a First-Mover Advantage in Agentic Commerce?

    November 4, 2026
    embedded finance for isvs

    Embedded Finance Is Reshaping the Growth Strategy for Software Companies

    November 3, 2026
    stripe privy

    With Agentic Commerce, the Wallet Will Be as Important as the Bot

    November 2, 2026

    Linkedin-in X-twitter
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter

    ©2026 PaymentsJournal.com |  Terms of Use | Privacy Policy

    • Commercial Payments
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    No Result
    View All Result