PaymentsJournal
No Result
View All Result
SIGN UP
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
PaymentsJournal
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
No Result
View All Result
PaymentsJournal
No Result
View All Result

The Difference between a Smart Contract and a Smart Legal Contract Explained

By Tim Sloane
September 24, 2021
in Analysts Coverage, Blockchain, Digital Assets & Crypto
0
0
SHARES
0
VIEWS
Share on LinkedIn
The Difference between a Smart Contract and a Smart Legal Contract Explained

The Difference between a Smart Contract and a Smart Legal Contract Explained

If interested in learning about smart contracts, not from a technologist, but from a lawyer that understands technology, this article in The National Law Review is for you! 

It opens with simple examples of what a smart contract is and what it does (I enjoyed the vending machine example).  Things get more interesting as smart contracts are evaluated based on existing Uniform Commercial Codes.  This is where the rubber starts to meet the road. 

The article also evaluates smart contracts versus smart legal contracts, which is obviously an important distinction, and categorizes common vulnerabilities smart contracts might exhibit. This article is well worth your time if trying to better understand contracts implemented in software (and references are available in the article):

“In addition, for the smart contract to constitute a legally binding contract for the sale of goods, the contract must also satisfy the various requirements of Article 2 of the Uniform Commercial Code (UCC),  including its statute of frauds requirements and its requirement that the contract set forth a quantity in order to be enforceable.5  Practitioners will need to evaluate on a case-by-case basis whether a smart contract meets these elements and therefore represents a binding legal contract for the sale of goods.

The Uniform Law Commission and the American Law Institute established a Uniform Commercial Code and Emerging Technologies Committee6 to study and evaluate the UCC in the context of “among other issues, distributed ledger technology, virtual currency, electronic notes and drafts, other digital assets, payments, and bundled transactions,” and the Uniform Law Commission released an issues memorandum7 discussing these topics in July 2021 following two years of committee meetings.  While smart contracts have been part of the discussion, no formal evaluation for smart contracts has been performed by the Uniform Law Commission or the American Law Institute, leaving open the opportunity for clearer guardrails in the future as to whether a smart contract amounts to a legal contract.

Smart Contracts vs. Smart Legal Contracts

Smart contracts are not to be confused with smart legal contracts.  While a smart contract is a computer program coded to effectuate an outcome upon the occurrence of a triggering event, a smart legal contract is “a legally binding agreement that is digital and able to connect its terms and the performance of its obligations to external sources of data and software systems.”8  The Accord Project makes clear that, although a smart legal contract can use smart contracts via blockchain technology, a smart legal contract can also be created using traditional software systems without the use of blockchain.9”
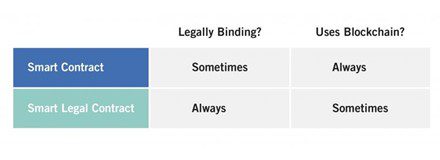
Photo Credit: The National Law Review.

Overview by Tim Sloane, VP, Payments Innovation at Mercator Advisory Group

0
SHARES
0
VIEWS
Share on LinkedIn
Tags: BlockchainLegislationSmart ContractsSmart Legal Contract

    Get the Latest News and Insights Delivered Daily

    Subscribe to the PaymentsJournal Newsletter for exclusive insight and data from Javelin Strategy & Research analysts and industry professionals.

    Must Reads

    bots fraud, bank security in data sharing, J.P. Morgan fraud protection TSYS, 3D Secure 2.0

    The Evolution of 3D Secure Puts it at the Center of Fraud Prevention

    September 18, 2026
    fraud detection signals

    Why Fraudsters Look Trustworthy and Good Customers Look Suspicious

    September 17, 2026
    Fraud Monitoring, Nacha ACH Rules, Same Day ACH

    10 Years Running, Same Day ACH Continues to Break New Ground

    September 16, 2026
    stablecoin infrastructure

    To Unlock Stablecoins’ Potential, Infrastructure Gaps Must Be Resolved

    September 15, 2026
    Latin America payment orchestration

    Navigating Latin America’s Complex Payment Ecosystem

    September 14, 2026
    upi biometric

    Beyond Authentication: Rethinking Digital Identity Security

    September 11, 2026
    Fraud Monitoring, Nacha ACH Rules, Same Day ACH

    Nacha’s Upcoming Rules Refresh Is All About Improving Clarity

    September 10, 2026
    instant payments for financial institutions

    Why Haven’t More Financial Institutions Adopted Instant Payments?

    September 9, 2026

    Linkedin-in X-twitter
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter

    ©2026 PaymentsJournal.com |  Terms of Use | Privacy Policy

    • Commercial Payments
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    No Result
    View All Result
