PaymentsJournal
No Result
View All Result
SIGN UP
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
PaymentsJournal
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
No Result
View All Result
PaymentsJournal
No Result
View All Result

BNPL CFPB Reports: Will Line Items Look like CCs or Installment Loans?

By Brian Riley
February 28, 2022
in Analysts Coverage, Credit
0
0
SHARES
0
VIEWS
Share on LinkedIn
BNPL CFPB Reports: Will Line Items Look like CCs or Installment Loans?

BNPL CFPB Reports: Will Line Items Look like CCs or Installment Loans?

Today, the WSJ reports that Buy Now, Pay Later updates will begin at Equifax, with Experian and TransUnion soon to follow.

…OK, I jumped the gun this morning to see if the many BNPL plans I opened and paid were on my credit file at the central site, www.myannualcreditreport.com. When I looked at all three bureaus, the only sign that I ever applied or paid for a BNPL loan was shown as an Affirm purchase from Walmart. Interestingly, the update was at Experian for a $245 transaction, marked “paid, closed/never late.”

That is the only item so far, with Experian, not Equifax, as WSJ mentioned. In any event, the reporting was accurate. In January 2021, we documented my field research, which began with American Express’ Plan It Pay It in March 2019, followed by PayPal, on my 22-year old account that insulates me from internet merchants and scammers.

Following that, it continued with Afterpay and Affirm. The research continued in the 2021 winter holiday season, and I did a few more. You can find a summary of those events in this Mercator Viewpoint: BNPL Borrowing: Confessions of a Credit Card Manager.

One of the reasons to follow through with the three credit bureaus is to see if the reporting is consistent. For example, the WSJ article mentions, “Equifax will classify pay-in-four loans as either revolving credit lines or installment loans on your report.”

That’s my issue. Aren’t BNPL loans installment lines of credit?

How FICO Scores measure things is essential. As previously mentioned, my wife has a better FICO Score than me because I like to field test credit card offers. Call me a points-hog, but that’s how I roll.

According to the FICO Site, where they review the history of the score, these are the main attributes used in building the score.

  • Loan repayment history
  • Amounts owed
  • Length of credit history
  • New credit accounts
  • Credit applications
  • Types of credit used

And, not all attributes are treated the same:
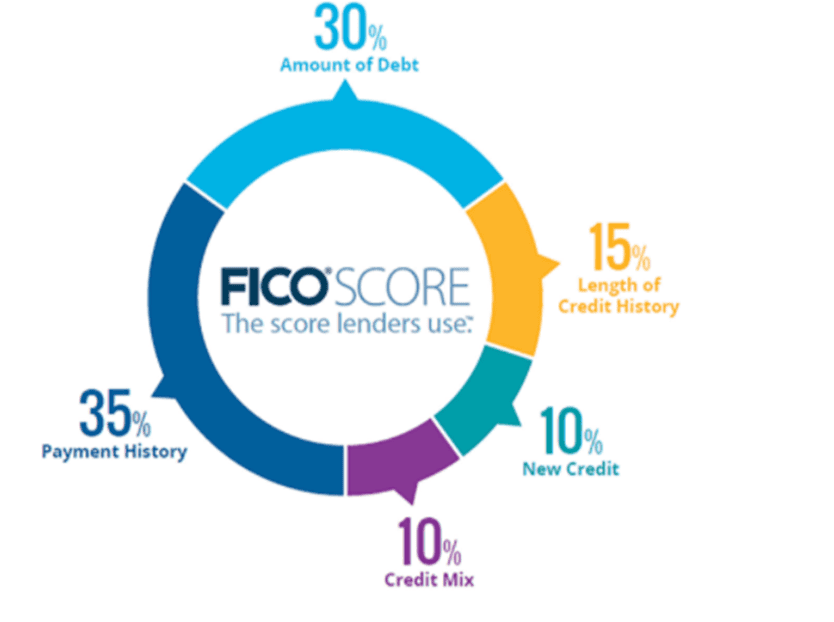
So, based on the lack of a standard way to report a BNPL Loan, whether it be installment or revolving, the bureaus can report inconsistent data into the FICO Score metric.

The numbers would be the same for the amount of debt, length of credit history, payment history, but the credit mix will be different. With the three top bureaus reporting, hopefully there is some common definition of what’s what now that BNPL is on the regulatory radar.

Who knows, maybe we’ll get back to the consistency on scores after the process settles. But for now, see the reporting as a significant step towards maturing the BNPL product.

Overview by Brian Riley, Director, Credit Advisory Service at Mercator Advisory Group

0
SHARES
0
VIEWS
Share on LinkedIn
Tags: BNPLBuy Now Pay LaterCFPBCreditCredit ScoreEquifaxExperianFICOTransUnion

    Get the Latest News and Insights Delivered Daily

    Subscribe to the PaymentsJournal Newsletter for exclusive insight and data from Javelin Strategy & Research analysts and industry professionals.

    Must Reads

    Secured Credit Cards, Biometrics Integration Smart Cards, digital banking transformation

    Turning Digital Banking Into a Lending Opportunity

    November 13, 2026
    ai synthetic identity fraud

    Identity Crisis: The AI-Powered Rise of Synthetic Identity Fraud

    November 12, 2026
    first-party fraud prevention

    How Automation Is Changing the Fight Against First-Party Fraud

    November 11, 2026
    agentic payments governance

    From Know Your Agent to Govern Your Agent: Building the Control Layer for B2B Agentic Payments

    November 10, 2026
    merchant management APIs

    How Merchant Management APIs Are Streamlining Operations

    November 9, 2026
    digital wallet threats

    Why Digital Wallet Security Is Becoming More Complex

    November 6, 2026
    faster payments, Synchrony

    Just How Large Is the Potential Market for Stablecoins?

    November 5, 2026
    agentic commerce strategy

    Will There Be a First-Mover Advantage in Agentic Commerce?

    November 4, 2026

    Linkedin-in X-twitter
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter

    ©2026 PaymentsJournal.com |  Terms of Use | Privacy Policy

    • Commercial Payments
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    No Result
    View All Result


