PaymentsJournal
No Result
View All Result
SIGN UP
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
PaymentsJournal
  • Commercial
  • Credit
  • Debit
  • Digital Assets & Crypto
  • Digital Banking
  • Emerging Payments
  • Fraud & Security
  • Merchant
  • Prepaid
No Result
View All Result
PaymentsJournal
No Result
View All Result

Credit Card Portfolios Slide: Lower FICO Scores, Steal a Co-Brand, or Loosen Up Lending

By Brian Riley
July 6, 2021
in Analysts Coverage, Credit, Debt, Lending
0
0
SHARES
0
VIEWS
Share on LinkedIn
Credit Card Portfolios Slide: Lower FICO Scores, Steal a Co-Brand, or Loosen Up Lending

Credit Card Portfolios Slide: Lower FICO Scores, Steal a Co-Brand, or Loosen Up Lending

Based on Bloomberg numbers, nine top credit card portfolios continue to show negative growth. The Financial Times illustrates credit card YoY loan growth as a percentage of the prior period. Portfolio shortfalls range from 9% at Discover to 21% at PNC.
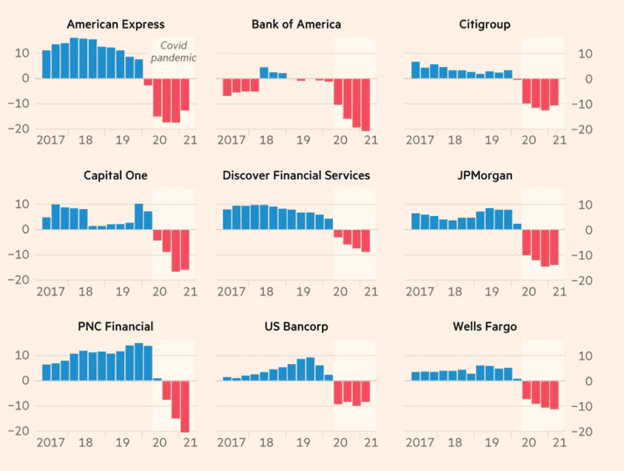
The good news is that 2Q21 revenue should hold well, as credit card issuers continue to release loan loss reserves after Stress Tests indicated that the future would be less risky as expected.  The bad news is that the cushion will be gone by 3Q21, so it is time to market.

  • Loan balances slid between 9 and 14 percent yearly among the largest credit card lenders, including JPMorgan, Citigroup, and Discover in the first quarter. So now, those lenders are at the forefront of a marketing blitz that is accelerating into the summer months. 
  • According to Competition, online solicitations for new card customers jumped 85 percent last month year on year as lenders trotted out enhanced rewards, higher credit limits, and low promotional rates.
  • Even with the surge, overall balance transfer offers are still at only 50 percent of 2019 levels.

This is not the first time in recent years where issuers scramble to bulk up their portfolios. If they do not, they will feel the pain with reductions in interest revenue and interchange. With collection volume down, now is a good time for some aggressive lend

  • Last month Citigroup, Bank of America, and Capital One doled out unsolicited credit line increases to some customers with good credit history, raising those limits by as much as a third, according to offers reviewed by the FT and Competiscan data. Citigroup led the pack with the most increased notifications, according to Competiscan.

Collections are under control, and many issuers have their loss rates in the bag for 2021. Now, it is time to beef up solicitations and underwriting to build the revenue stream. If done effectively, 2022 will be off to a good start. If not, expect 2022 to start off in the red!

Overview provided by Brian Riley, Director, Credit Advisory Service at Mercator Advisory Group

0
SHARES
0
VIEWS
Share on LinkedIn
Tags: Bank of AmericaCapital OneCitigroupCredit CardCredit Card IssuerDebtLoans

    Get the Latest News and Insights Delivered Daily

    Subscribe to the PaymentsJournal Newsletter for exclusive insight and data from Javelin Strategy & Research analysts and industry professionals.

    Must Reads

    synthetic identity fraud

    Synthetic Identity Fraud Is Surging—and Often Goes Unnoticed

    October 9, 2026
    Gift cards

    Lessons from the Gift Card Forum: The Critical Shift from Breakage to Redemption

    October 8, 2026
    AI-powered fraud prevention

    In the Escalating Fraud Fight, Industry Solidarity Is Imperative

    October 7, 2026
    ownership authentication

    Ownership Authentication: Fighting Fraud Losses and First-Party Risk

    October 6, 2026
    detecting scams

    In a Faster World, Identity Protection Hinges on Predicting Scams

    October 5, 2026
    mobile banking

    Mobile Banking Has the Tools. Now Banks Need to Guide Customers

    October 2, 2026
    ai aml

    Getting Out in Front of Agentic Commerce Fraud

    October 1, 2026
    payment authentication

    Developing Digital Trust Hinges on Unifying Authentication Methods

    September 30, 2026

    Linkedin-in X-twitter
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Commercial
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Digital Banking
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter
    • About Us
    • Advertise With Us
    • Sign Up for Our Newsletter

    ©2026 PaymentsJournal.com |  Terms of Use | Privacy Policy

    • Commercial Payments
    • Credit
    • Debit
    • Digital Assets & Crypto
    • Emerging Payments
    • Fraud & Security
    • Merchant
    • Prepaid
    No Result
    View All Result